When you need extra cash in India, two popular options often appear on the table: a personal loan from a bank or NBFC, and a credit card loan (often called a credit card EMI or cash advance). Both can provide quick funds, but they work very differently. This guide breaks down the key aspects—interest rates, eligibility, repayment flexibility, hidden costs, and practical tips—so you can choose the product that best matches your financial situation.
A personal loan is an unsecured loan offered by banks, public sector lenders, private banks, and non‑bank financial companies (NBFCs). You receive a lump‑sum amount that you repay in fixed monthly installments (EMIs) over a predetermined tenure, usually 12‑60 months.
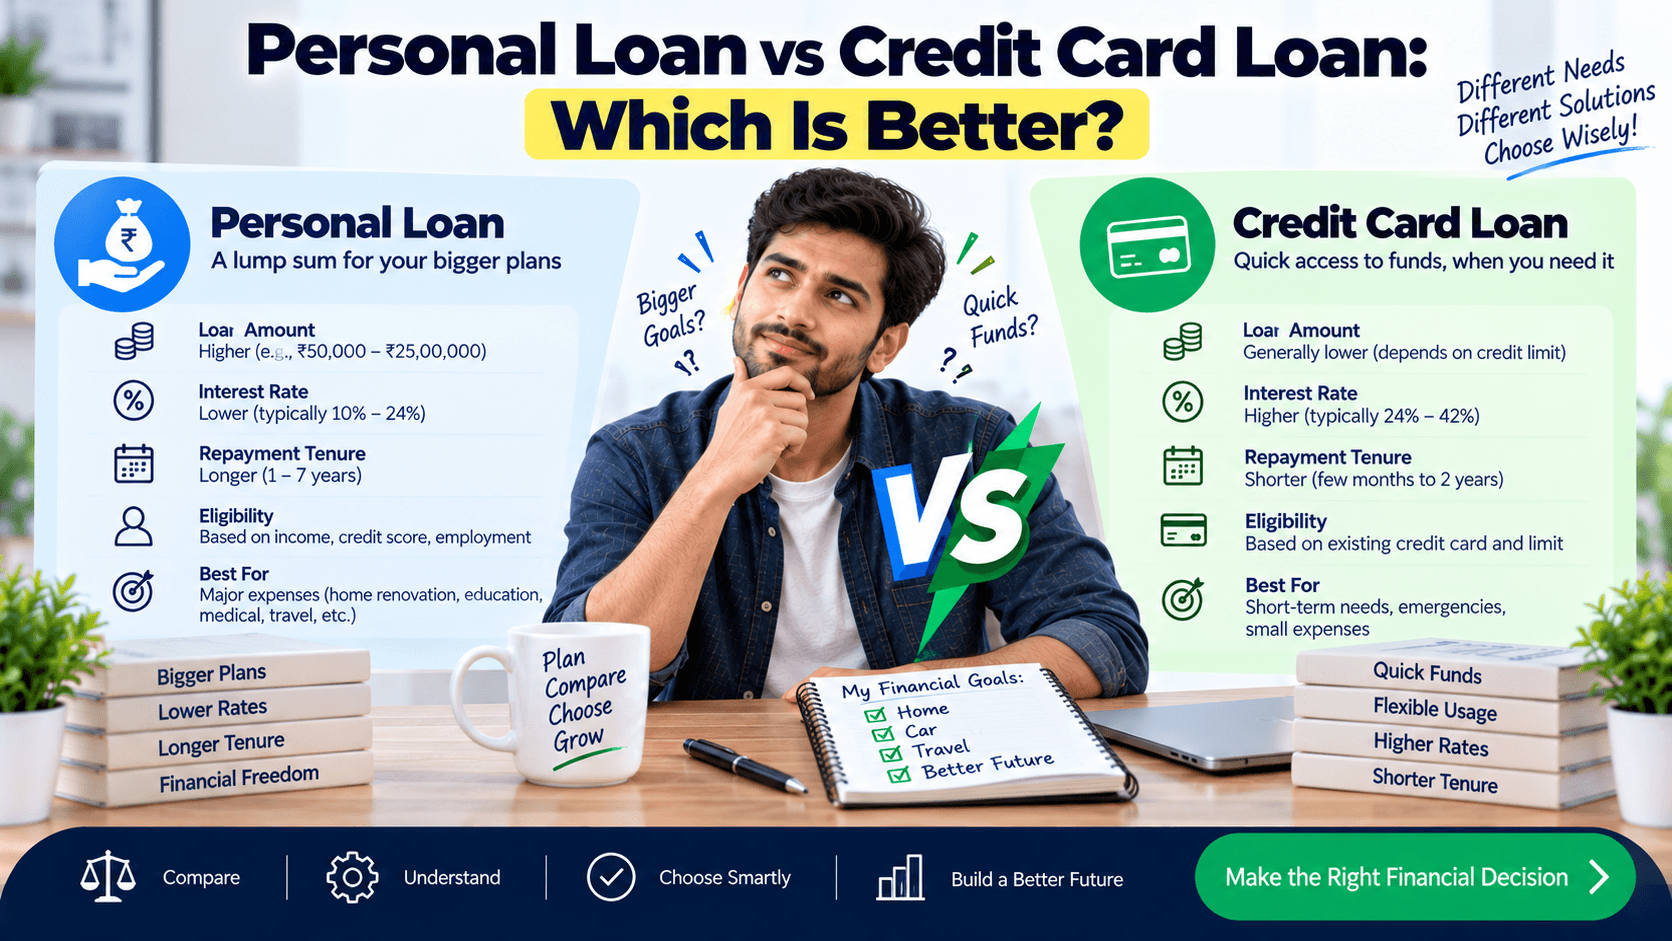
Typical loan amount: ₹50,000 – ₹10 million
Tenure: 12 – 60 months (some lenders extend up to 84 months)
Disbursement: Within 1‑3 business days after approval
A credit card loan can refer to two related facilities:
Cash Advance: You withdraw cash against your credit limit, usually at a higher interest rate.
EMI Conversion: You convert a high‑value purchase or outstanding balance into fixed‑rate EMIs.
Both are extensions of your credit card limit, and you repay either as a minimum amount each month (cash advance) or as a structured EMI plan (conversion).
Personal Loan: Interest rates in India typically range from 9.5% p.a. to 24% p.a. Public sector banks often offer the lower end for salaried borrowers, while NBFCs may charge higher rates but provide quicker approvals.
Credit Card Loan: Cash advances carry rates around 24% p.a. to 36% p.a. EMI conversion rates are slightly lower, usually 15% p.a. to 28% p.a., but still higher than the best personal loan offers.
**Bottom line:** For low‑cost borrowing, a personal loan usually wins.
Personal Loan: Requires proof of income (salary slips, Form 16, ITR), identity, address, and sometimes a bank statement. Many banks have a minimum salary requirement (₹15,000 – ₹25,000 per month).
Credit Card Loan: You only need an existing credit card with sufficient unused limit. No separate income proof is needed, though the bank may assess your credit score.
**Bottom line:** If you already have a credit card and need a small amount quickly, a credit card loan is more convenient.
Personal loans usually take 1‑3 days after document verification. Some digital lenders claim instant disbursal within minutes, but the average is a few days.
Credit card cash advances are instantaneous at ATMs or bank counters, while EMI conversion is processed within 24 hours.
Personal Loan: Fixed EMIs; you can pre‑pay partially or fully (often with a small pre‑payment penalty of 1‑2%).
Credit Card Loan: Cash advances require at least the minimum amount each month; if you miss, interest compounds daily. EMI conversion offers fixed EMIs but may not allow pre‑payment without fees.
**Bottom line:** Personal loans give clearer repayment schedules and cheaper pre‑payment options.
CostPersonal LoanCredit Card LoanProcessing fee0.5% – 2% of loan amount2% – 3% of cash advanceLate payment penalty2% – 4% of overdue amount2% – 5% of overdue amountPre‑payment chargesUsually 1% – 2%Often not allowed for cash advancesAnnual feeNoneCredit card annual fee (₹500 – ₹2,500)
You need a sizable amount for a one‑time project and prefer low interest. A personal loan of ₹3 Lakh at 11% p.a. for 36 months results in an EMI of roughly ₹10,200.
Using a credit card EMI conversion at 22% p.a. would raise the EMI to about ₹12,400, plus a processing fee of ₹9,000. In this case, the personal loan is clearly cheaper.
You need cash today for an unexpected medical bill. Your credit card has a ₹50,000 unused limit. A cash advance of ₹30,000 at 30% p.a. will cost about ₹75 per day in interest, but you get the cash instantly.
If you apply for a personal loan, the minimum disbursal might be ₹50,000, and approval could take 2 days. For an emergency, the credit card cash advance wins despite higher cost.
Calculate the effective cost. Use an online EMI calculator for personal loans and a credit card interest calculator for cash advances. Compare the total interest payable over the intended tenure.
Check your credit score. A score above 750 fetches better personal loan rates. If your score is lower, a credit card loan might be the only immediate option.
Consider the loan purpose. For short‑term, low‑amount needs (<₹1 Lakh), a credit card loan can be convenient. For medium to large amounts (>₹2 Lakhs) and longer repayment, go for a personal loan.
Watch out for fees. Add processing fees, pre‑payment penalties, and any annual card fees to your total cost.
Negotiate. Some banks allow you to waive processing fees if you have a savings account with them or if you opt for auto‑debit of EMIs.
Maintain discipline. Avoid using credit card cash advances repeatedly; they can quickly spiral due to high interest and impact your credit utilization ratio.
Both personal loans and credit card loans have their place in an Indian consumer’s financial toolkit. If you need a larger amount, lower interest, and a predictable repayment schedule, a personal loan is generally the better choice. If you need cash instantly, the amount is modest, and you already have a credit card with a good limit, a credit card loan can be a convenient stop‑gap—provided you are aware of the higher cost.
Always run the numbers, read the fine print, and choose the product that aligns with your repayment ability and financial goals. A disciplined approach will keep your credit health strong and save you money in the long run.