Personal loans have become a popular way for Indians to meet short‑term financial needs – from wedding expenses to home renovation, medical emergencies, or consolidating credit‑card debt. While the application process is relatively quick, the interest rate you end up paying can vary widely. Understanding what determines that rate helps you plan better and, more importantly, negotiate a cheaper loan.
In India, personal loan interest rates are not fixed by law. Each lender (banks, NBFCs, fintechs) decides the rate based on a combination of regulatory guidelines and internal risk models. The Reserve Bank of India (RBI) influences the overall cost of borrowing through the repo rate, but the final rate you see on a personal loan agreement is a product of many individual factors.
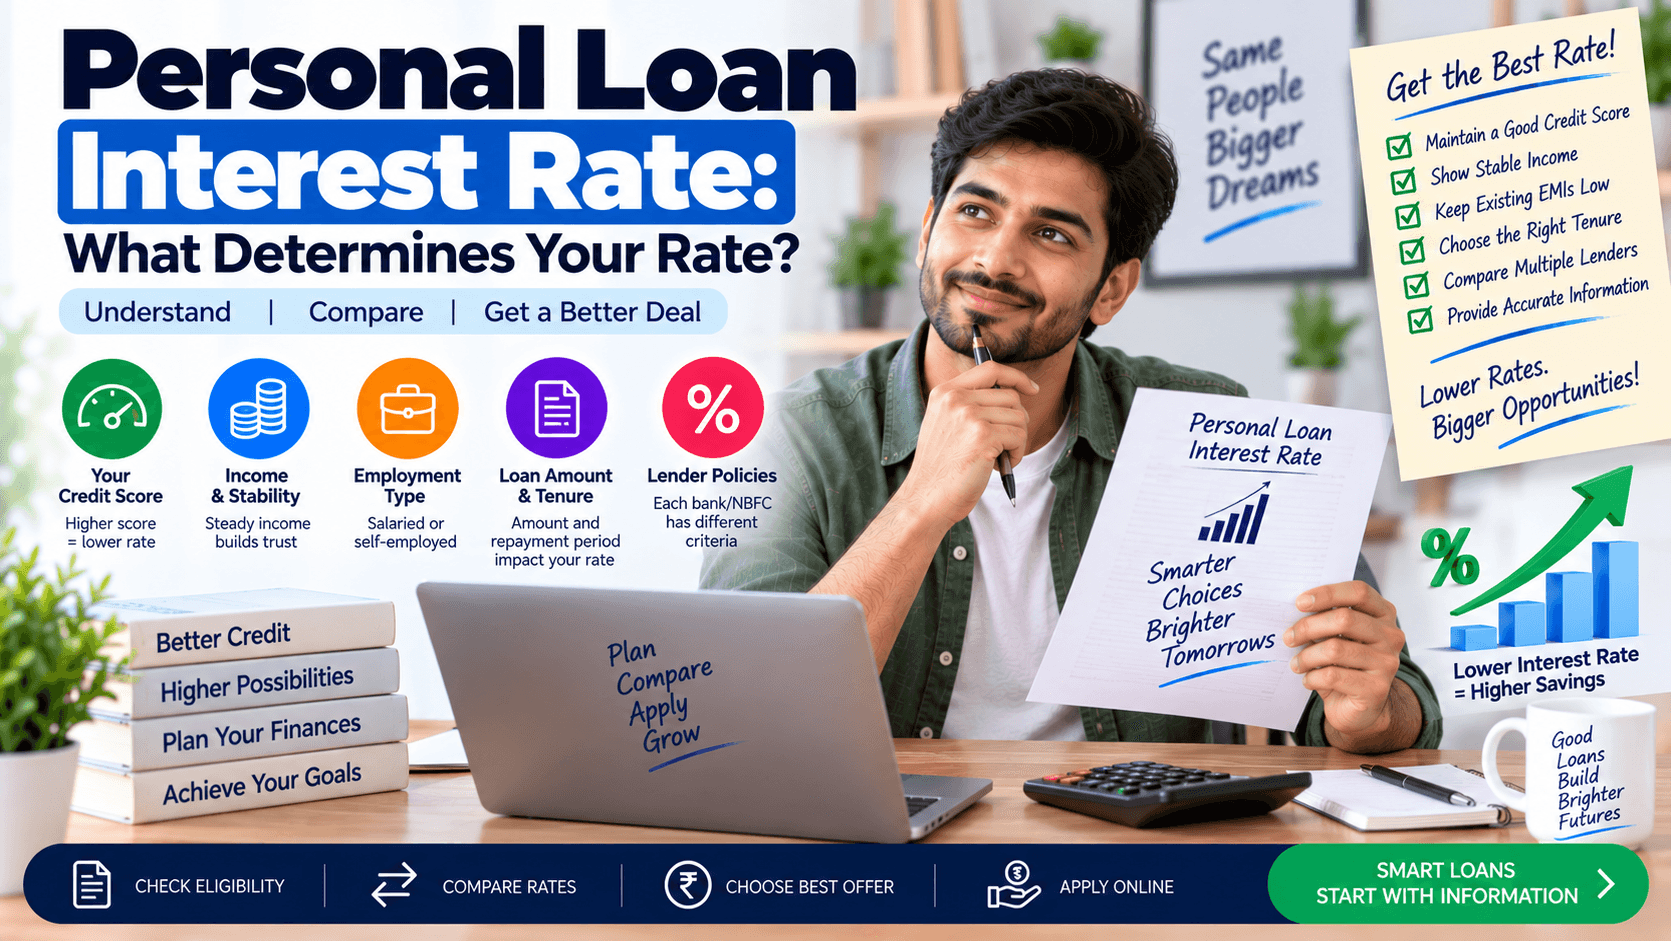
Your credit score is the single most important factor. A score above 750 usually places you in the "low‑risk" bucket, allowing lenders to offer rates as low as 9‑10% p.a. Scores between 650‑749 attract mid‑range rates (11‑13% p.a.), while a score below 650 can push the rate beyond 15%.
The RBI’s repo rate is the benchmark for the entire banking system. When the RBI cuts the repo rate, banks typically lower their personal loan rates after a short lag. Conversely, a hike in the repo rate usually translates into higher loan rates.
Higher loan amounts: Larger loans often come with slightly lower rates because the lender’s fixed‑costs are spread over a bigger principal.
Shorter tenure: A 12‑month loan is generally cheaper than a 60‑month loan, as the lender’s exposure to credit risk is for a shorter period.
Traditional public sector banks (PSBs) tend to offer the most competitive rates, followed by large private banks. Non‑Bank Financial Companies (NBFCs) and fintech platforms may charge higher rates but compensate with faster approvals and fewer documentation requirements.
If you already have a salary account, credit‑card, or mortgage with the same bank, you may qualify for a "preferred customer" rate, often 0.5‑1% lower than the standard slab.
Some lenders differentiate between "general" personal loans and those earmarked for specific purposes (e.g., education, travel). Loans for well‑defined purposes sometimes attract marginally better rates because the lender can assess the risk more precisely.
Boost Your Credit Score: Pay existing credit‑card bills on time, clear any overdue dues, and avoid taking on multiple new loans within a short span.
Opt for a Shorter Tenure: Even if the EMI is a bit higher, the overall interest outflow will be lower.
Consider a Secured Personal Loan: If you can pledge a fixed deposit or a property, many banks offer rates 1‑2% below unsecured rates.
Shop Around: Use comparison portals like PaisaBazaar, BankBazaar, or MoneyControl to get a snapshot of rates from multiple lenders.
Negotiate: If you have a good banking relationship, ask the loan officer for a rate discount or waiver of processing fees.
Use Your Salary Account: Many Indian banks give a "salary‑account holder" discount on personal loan rates.
Avoid Unnecessary Add‑ons: Features like insurance cover or processing fee waivers can increase the effective cost of the loan.
Myth: "All personal loans have the same rate across banks."
Reality: Rates can differ by up to 5% between lenders.
Myth: "A lower rate always means lower total cost."
Reality: Fees, pre‑payment penalties, and loan tenure also affect the total cost.
Myth: "Only credit score matters."
Reality: While crucial, other factors like RBI policy and loan tenure are equally important.
Personal loan interest rates in India are a blend of macro‑economic signals from the RBI, your personal credit profile, the loan’s size and tenure, and the lender’s own risk appetite. By improving your credit score, choosing a suitable tenure, leveraging existing banking relationships, and comparing offers diligently, you can often shave 1‑2% (or more) off the quoted rate, translating into substantial savings over the life of the loan.
Remember, the cheapest loan on paper may not be the cheapest in practice. Always calculate the effective annual percentage rate (EAPR) that includes processing fees, insurance, and any hidden charges before signing the agreement.