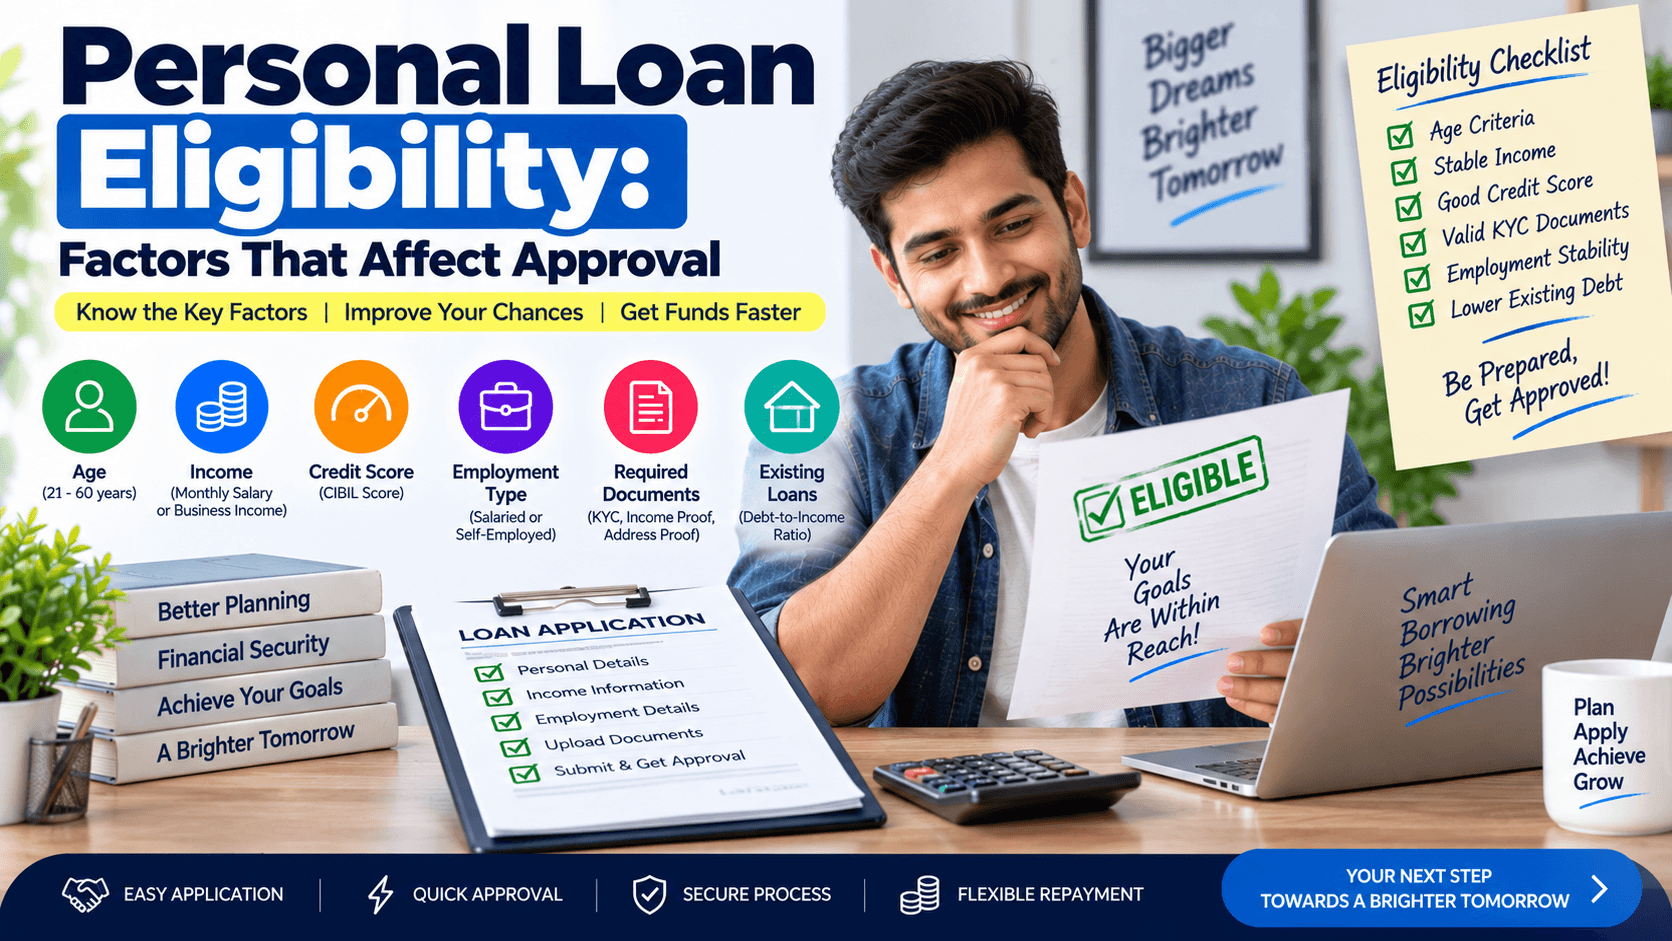
Personal loans are a popular way to fund education, medical emergencies, home renovations, or any unexpected expense. However, getting approved isn’t just about submitting an application; banks and NBFCs evaluate a range of criteria before handing over the funds. Knowing these factors can help you prepare a stronger case and improve your chances of getting the loan you need.
In India, the credit score is the single most important metric. A score above 750 is considered good and significantly boosts approval odds. Lenders look at:
Timely repayment of existing loans and credit cards
Number of credit inquiries in the last six months
Any defaults or settled accounts
Actionable tip: Check your credit report on CIBIL or other bureaus regularly, and clear small overdue amounts to raise your score before applying.
Consistent cash flow reassures lenders that you can service the loan. The common benchmarks are:
Minimum monthly net income of ₹25,000 for salaried individuals (higher for self‑employed)
Employment tenure of at least 2 years with the current employer
For self‑employed, at least 2 years of profitable business history and audited financial statements
Tip: If you’ve recently received a salary hike or bonus, wait until it reflects in your payslips before applying.
Lenders calculate how much of your monthly income is already tied up in existing liabilities. A DTI below 40% is generally preferred. To improve this ratio:
Pay down credit card balances
Avoid taking new loans a few months before applying
Consolidate high‑interest debts, if possible
Most banks require borrowers to be between 21 and 60 years old at loan maturity. Indian residents with a valid PAN and Aadhaar are eligible; NRIs need a stable Indian income source.
Incomplete or inaccurate documentation can delay or reject an application. Essential papers include:
Identity proof (Aadhaar, PAN)
Address proof (electricity bill, rental agreement)
Income proof (salary slips for 3 months, Form 16, or audited profit & loss for self‑employed)
Bank statements for the last 6 months
Employment verification letter (if required)
Tip: Keep scanned copies ready in PDF format to speed up online applications.
Improve Your Credit Score Early: Pay all dues before the statement date, keep credit utilization below 30%, and avoid multiple loan inquiries in a short span.
Show Consistent Income: Submit the latest salary slip and a clear employment letter. If you receive a bonus, attach the bonus letter as supplemental proof.
Reduce Existing Debt: Prioritize clearing high‑interest credit card balances; this instantly lowers your DTI.
Choose the Right Lender: Some NBFCs have flexible criteria for self‑employed borrowers, while traditional banks may offer lower interest rates for high credit scores.
Leverage Co‑Applicants: Adding a spouse or parent with a strong credit profile can improve the overall eligibility.
Maintain a Clean Banking History: Avoid frequent overdrafts and bounced cheques; they raise red flags during the verification process.
Applying for a loan amount that far exceeds your repayment capacity.
Submitting outdated documents (e.g., old salary slips).
Ignoring the impact of recent credit inquiries.
Providing inconsistent information across different forms.
Neglecting to disclose existing loans, leading to a higher DTI after verification.
Personal loan eligibility in India hinges on a mix of creditworthiness, stable income, manageable debt, and proper documentation. By proactively addressing each factor—especially your credit score and DTI—you can position yourself as a low‑risk borrower and increase the likelihood of approval. Use the tips above to prepare a complete, accurate application and negotiate the best terms available.