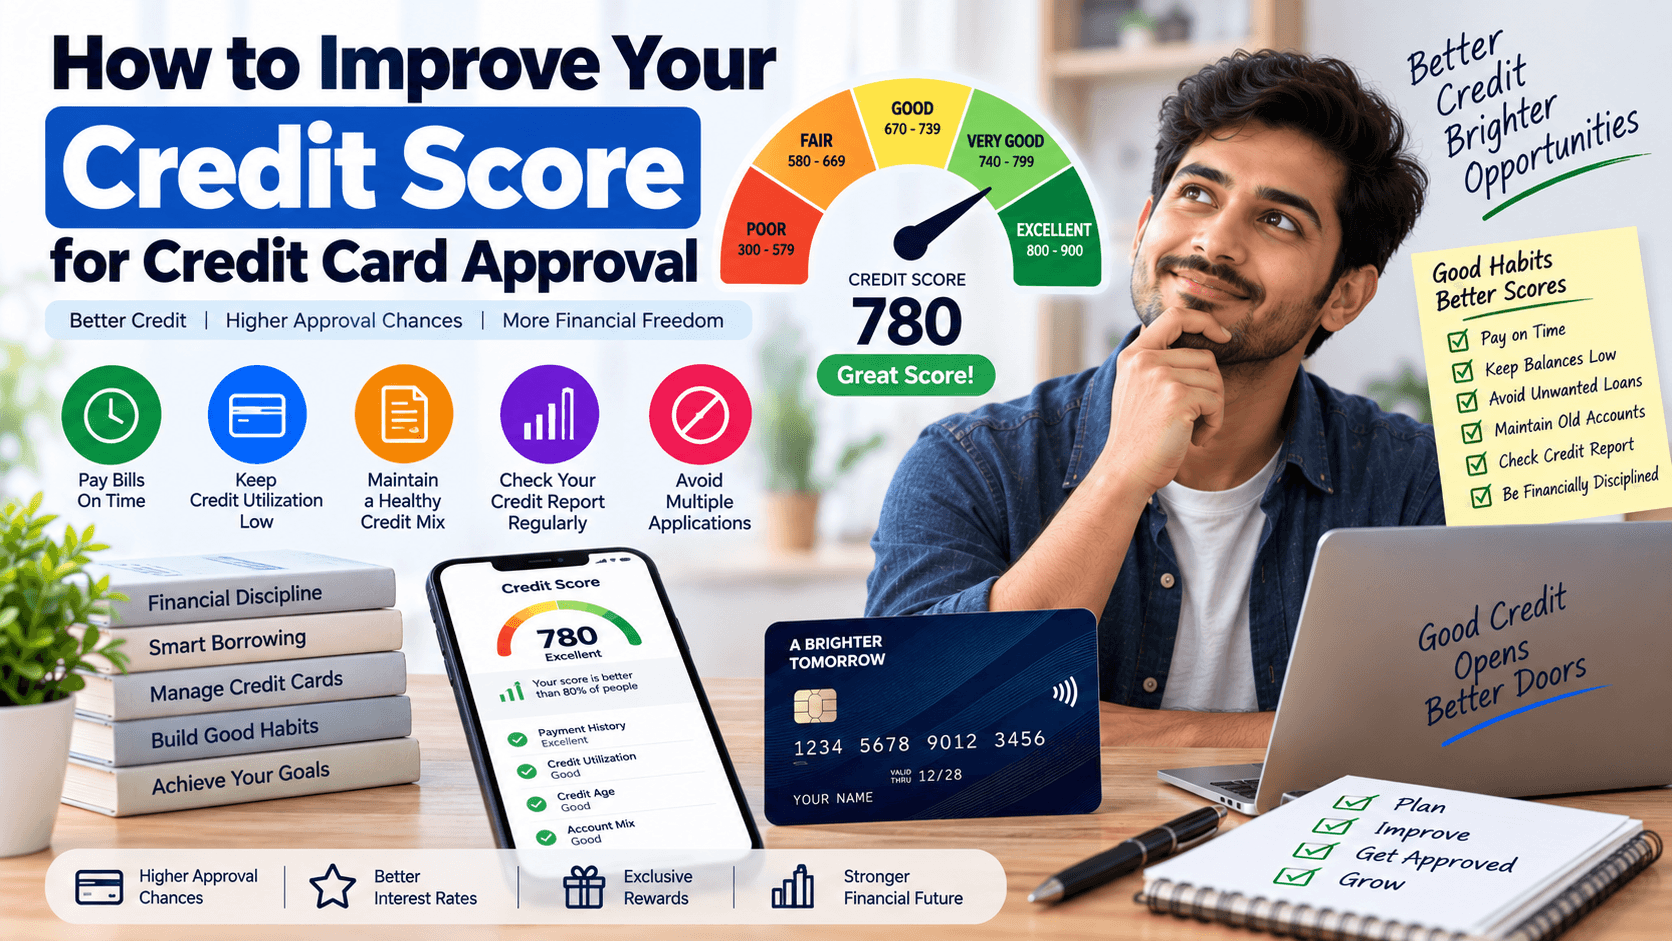
A credit score is a three‑digit number that reflects how you manage credit. In India, the most widely used scores are from CIBIL, Experian, Equifax and CRIF High Mark, ranging from 300 to 900. Lenders look at this score when you apply for a credit card, personal loan, or mortgage. A score above 750 is generally considered good and gives you a higher chance of approval with better interest rates and credit limits.
Credit card issuers use your score to gauge the risk of lending you money. A higher score signals that you pay your dues on time, keep balances low, and don’t over‑extend yourself. This translates into:
Higher probability of getting the card you want
Better credit limits
Lower annual fees and attractive reward programs
Preferential interest rates on cash advances
If your score is below 650, many banks may either reject your application or offer a secured credit card with a higher deposit requirement.
Payment history accounts for about 35% of your credit score. Set up auto‑debit or reminders for credit card EMIs, loan instalments, utility bills, and mobile connections. Even a single missed payment can stay on your credit report for up to 24 months.
Credit utilisation is the ratio of your total outstanding credit to your total credit limit. Aim to stay below 30% – ideally under 10% – on each card and overall. For example, if your combined limit is ₹1,00,000, keep the total balance under ₹30,000.
Each time a bank checks your credit report for a new card or loan, a hard enquiry is recorded. Multiple enquiries within a short span can dip your score by a few points. Space out applications and use “pre‑approval” features offered by many Indian banks to get a soft check first.
Lenders like to see a mix of credit types – credit cards, personal loans, auto loans, or a home loan. If you only have a credit card, consider taking a small personal loan (e.g., ₹50,000) and repaying it on time. This demonstrates responsible handling of different credit products.
The length of credit history contributes about 15% to your score. Closing an old credit card reduces the average age of your accounts and can slightly lower your score. Keep the card active by using it for small purchases and paying them off each month.
Every Indian consumer is entitled to a free credit report once a year from each bureau. Review it for errors such as wrong personal details, duplicate accounts, or incorrect payment statuses. Dispute any inaccuracies promptly; corrections can improve your score quickly.
If you have a low score or no credit history, a secured credit card (where you lock a cash deposit as collateral) can be a stepping stone. Use it responsibly, keep utilisation low, and pay the balance in full each month. After 6‑12 months of good behaviour, many banks will transition you to an unsecured card and delete the secured tag.
Set up auto‑pay for all EMIs and credit card bills before the due date.
Check your combined credit utilisation; aim for <30%.
Log into CIBIL/Experian portal and verify your report for errors.
If you plan a new card, wait at least 90 days after the last hard enquiry.
Make at least one small purchase on each old credit card and clear it immediately.
Once you have nudged your score above 750, follow these steps for a smoother approval process:
Choose the right card: Look for cards that match your spending habits – travel, groceries, online shopping, etc. Compare annual fees, reward points, and interest rates.
Check pre‑approval offers: Many banks show a ‘pre‑approved’ banner on their website. This indicates a soft check, meaning no impact on your score.
Gather documents: PAN, Aadhaar, recent salary slip or ITR, and proof of residence.
Fill the online application: Ensure all details match your credit report to avoid mismatches.
Follow up: If the decision is pending, call the bank’s helpline and ask for the status. Sometimes, providing a recent bank statement can accelerate approval.
My salary determines my credit limit. While income is a factor, your credit score and utilisation history have a bigger impact.
Closing a card improves my score. Closing reduces total available credit and can raise utilisation, hurting your score.
Only credit cards affect my score. Loans, overdrafts, and even settled accounts play a role.
Improving your credit score is a gradual process, but with disciplined payments, low utilisation, and regular monitoring, you can see noticeable gains within 3‑6 months. A higher score not only unlocks better credit card offers but also paves the way for cheaper loans and smoother financial transactions. Start implementing these tips today, and watch your creditworthiness rise.