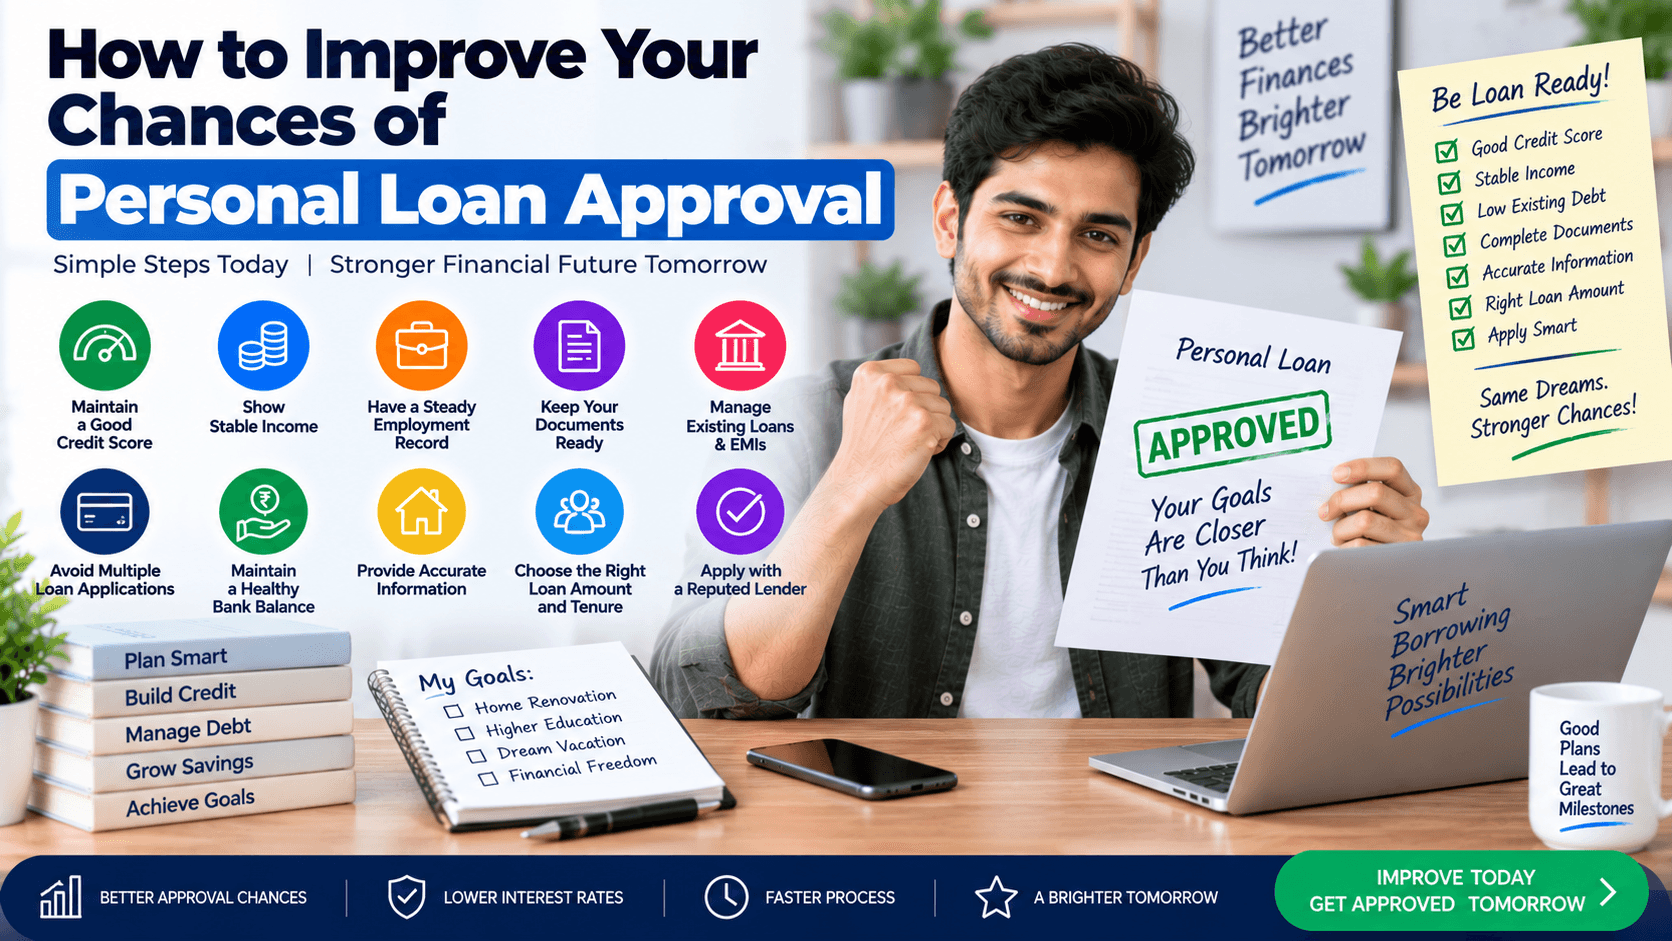
Before you start applying, it helps to know what Indian banks and NBFCs look for. The core factors are:
Credit score (typically 650+ for mainstream lenders)
Stable income – salaried or self‑employed with at least 2‑3 years of consistent earnings
Debt‑to‑income (DTI) ratio – ideally below 40%
Age and residency – usually 21‑60 years and Indian resident
Meeting these basics doesn’t guarantee approval, but it puts you in the right lane.
Obtain your credit report from CIBIL, Experian, Equifax or CRIF. Look for errors such as misspelled names, wrong loan amounts, or outdated defaults. Dispute any mistake – it can add 20‑30 points instantly.
Credit cards, EMIs, and utility bills that are paid before the due date send a positive signal to lenders. Set up auto‑debits or reminders to avoid late payments.
Pay down high‑interest credit‑card balances first. A lower credit utilization (below 30%) improves the score faster than opening a new account.
Each loan application generates a hard inquiry that can drop the score by a few points. Apply only when you have a strong profile and after checking eligibility through soft‑pull tools.
Missing or incomplete paperwork is the most common reason for rejection. Keep these documents ready in PDF format:
Identity proof – AADHAAR, PAN card, passport
Address proof – AADHAAR, electricity bill, rental agreement
Income proof – Latest salary slips (last 3 months) and Form 16 for salaried; IT returns, profit & loss statement, and bank statements for self‑employed
Bank statements – Last 6 months showing regular inflow
Employment proof – Offer letter or service certificate
Existing loan statements – To calculate DTI
Label each file clearly (e.g., "Salary_Slips_Jan‑Mar2024.pdf") to speed up the lender’s verification.
The DTI ratio is calculated as Total Monthly Debt Obligations ÷ Gross Monthly Income × 100. Lenders prefer it below 40%. If your ratio is higher:
Pay off a small personal loan or credit‑card debt before applying.
Consider a joint application with a co‑applicant who has a lower DTI.
Increase your income through a side gig and reflect it in the latest bank statements.
Not all lenders have the same risk appetite.
Public sector banks – Typically stricter on credit scores but offer lower interest rates.
Private banks – Slightly more flexible, faster processing, and may accept a slightly lower score.
NBFCs – Often cater to self‑employed borrowers; they may charge a higher rate but have lenient documentation.
Use online eligibility calculators (e.g., from SBI, HDFC, Axis, or Bajaj Finserv) to pre‑filter lenders where you are likely to qualify.
If your own profile is borderline, adding a co‑applicant with a strong credit history (spouse, parent) can improve approval odds dramatically. Alternatively, a secured personal loan backed by a fixed deposit or property reduces risk for the lender and often results in faster sanction.
Applying for a loan amount far higher than needed – it raises the DTI and may trigger rejection.
Submitting outdated salary slips or tax returns – lenders consider the most recent 3‑month salary and last 2‑year IT returns.
Ignoring pre‑approval offers – they give you a score‑based hint without a hard pull.
Having multiple pending loan applications – each hard enquiry compounds the risk.
Check your credit score and fix any errors.
Pay off high‑utilisation credit‑card balances.
Gather all identity, address, income and bank documents in PDF.
Calculate your DTI; aim for <40%.
Use at least two eligibility calculators to shortlist lenders.
If needed, add a co‑applicant or consider a secured loan.
Submit a single, well‑prepared application.
Following these steps can boost your personal loan approval chances from a tentative “maybe” to a confident “yes”. Remember, lenders value consistency, transparency, and a low risk profile above all.
Improving personal loan approval in India is not about luck; it’s about presenting a clean financial picture. By polishing your credit score, keeping documentation tidy, managing debt wisely, and choosing the right lender, you can turn the approval process into a smooth, predictable experience.