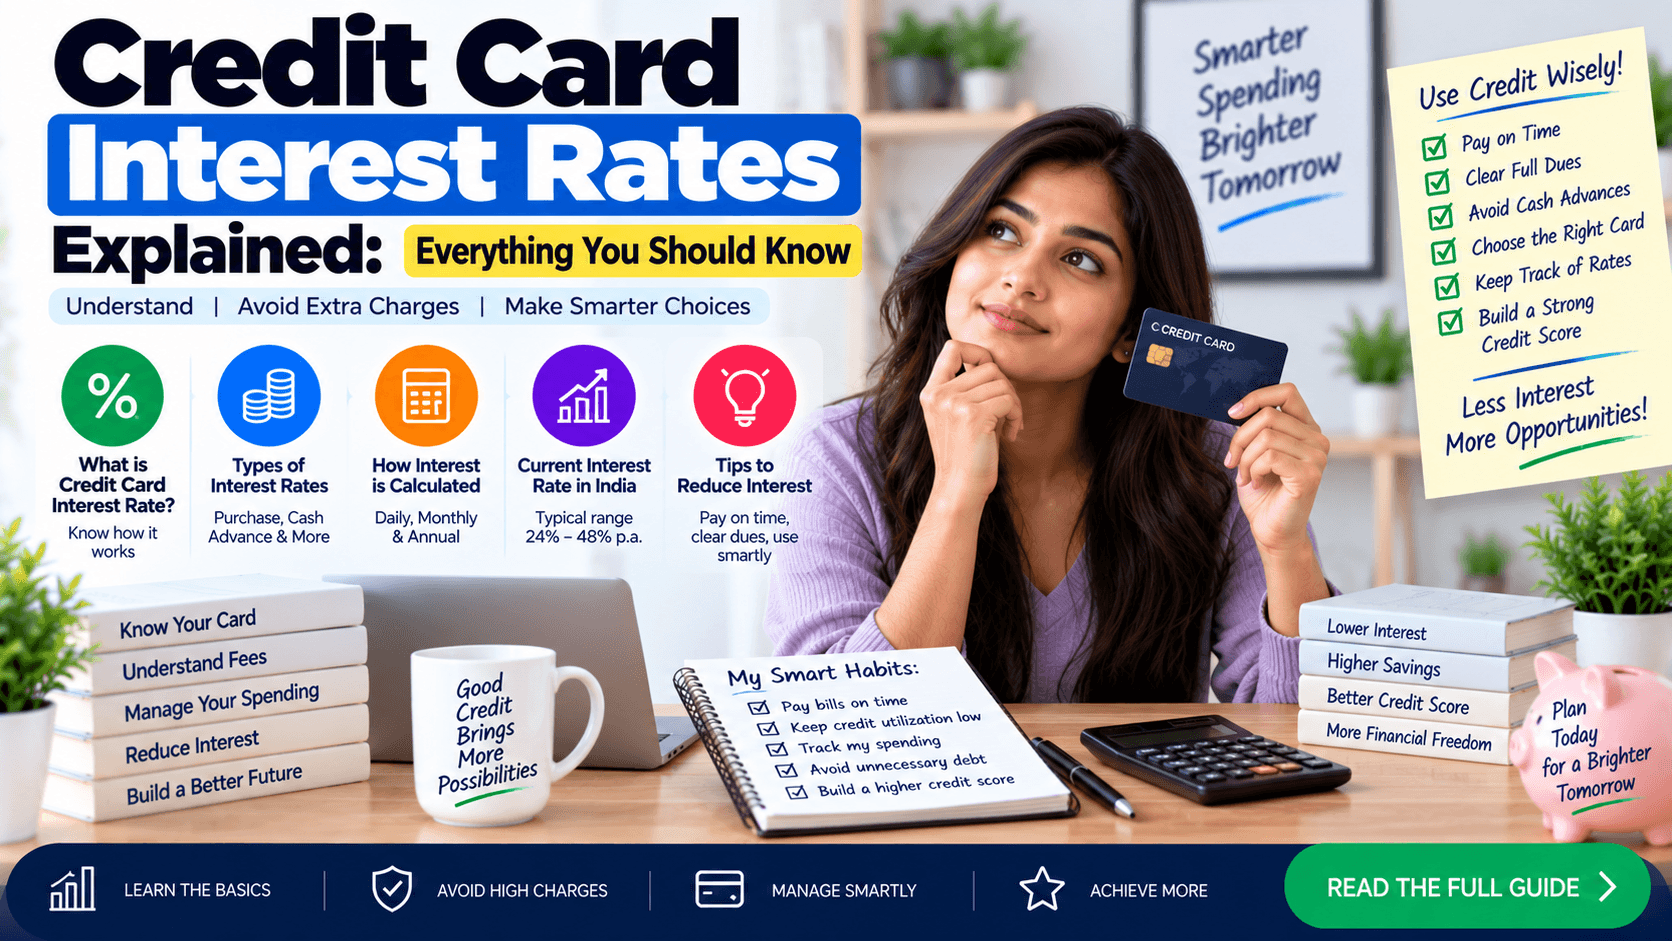
Credit cards are a convenient way to pay for everyday expenses, but the interest you pay can quickly turn a purchase into a costly affair. In India, credit card interest rates are expressed as an annual percentage rate (APR) and can vary widely between banks, card types, and even based on your credit profile. This guide breaks down the jargon, shows how interest is calculated, and provides practical steps to keep your costs low.
The APR is the total cost of borrowing on a yearly basis, including the interest rate and any other fees that are part of the credit agreement. Indian banks are required to disclose the APR on their brochures and websites, so you can compare cards side‑by‑side. A lower APR means you’ll pay less interest if you carry a balance.
Most Indian credit cards use a daily reducing balance method. Here’s a step‑by‑step illustration:
Step 1: The bank announces an annual interest rate, for example, 36% per annum.
Step 2: Convert the annual rate to a daily rate: Daily Rate = (Annual Rate ÷ 365) = 0.0986% per day.
Step 3: Each day, the bank applies this rate to the outstanding balance.
Step 4: At the end of the billing cycle, the daily interest amounts are summed up and added to the statement.
If you pay the full statement amount before the due date, you enjoy an interest‑free grace period (usually 45‑55 days). However, once you miss a payment, interest is charged on the entire balance from the date of purchase, not just the remaining amount.
This is the headline rate announced by the bank. Premium cards often have lower rates (e.g., 30% APR) compared to entry‑level cards (up to 42%).
Cash withdrawals on a credit card attract a higher interest rate, typically 3–5% above the base rate, and no grace period.
Missing the due date can add a flat fee (₹500–₹1,000) and trigger a higher penalty interest rate for the next cycle.
If you exceed your credit limit, banks may levy a fee and increase the interest rate on the excess amount.
Pay the Full Balance Every Month: This is the simplest way to avoid interest altogether.
Utilise the Grace Period Wisely: Make purchases early in the billing cycle so you have maximum days before the due date.
Set Up Automatic Payments: Ensure you never miss a due date, which protects you from penalty rates.
Prioritise High‑Interest Balances: If you must carry a balance, focus on paying off the card with the highest APR first.
Avoid Cash Advances: Use your debit card or a personal loan for cash needs; cash‑advance interest is costly.
Negotiate With Your Bank: Loyal customers with good credit scores can sometimes get a reduced rate if they request it.
Monitor Your Statement Regularly: Look out for hidden fees or unexpected interest charges and raise disputes promptly.
When selecting a card, consider more than just the reward points. Look at the following:
APR Comparison: Choose a card with an APR that fits your usage pattern.
Grace Period Length: Longer periods give you more flexibility to pay off purchases.
Fee Structure: Some cards waive annual fees for the first year; weigh this against a lower APR.
Credit Limit: A higher limit can reduce your credit utilisation ratio, which may improve your credit score over time.
"I only pay interest on the amount I didn’t pay": In India, once you miss a payment, interest is often calculated on the entire balance from the date of purchase.
"Interest stops after I pay the minimum amount": Paying only the minimum extends the repayment period and dramatically increases total interest paid.
"All fees are included in the APR": Some fees, like cash‑advance charges, are separate and can increase the effective cost.
Many Indian banks now offer mobile apps with built‑in calculators that show how much interest you’ll incur based on your current balance and payment schedule. Third‑party apps such as MoneyControl or ET Money also provide visualisations to help you plan payments.
Understanding how credit card interest rates work empowers you to make smarter financial decisions. By paying your balance in full, using the grace period, and choosing cards with competitive APRs, you can enjoy the convenience of credit cards without the burden of high interest charges.
Stay informed, keep an eye on your statements, and treat your credit card as a tool—not a trap.