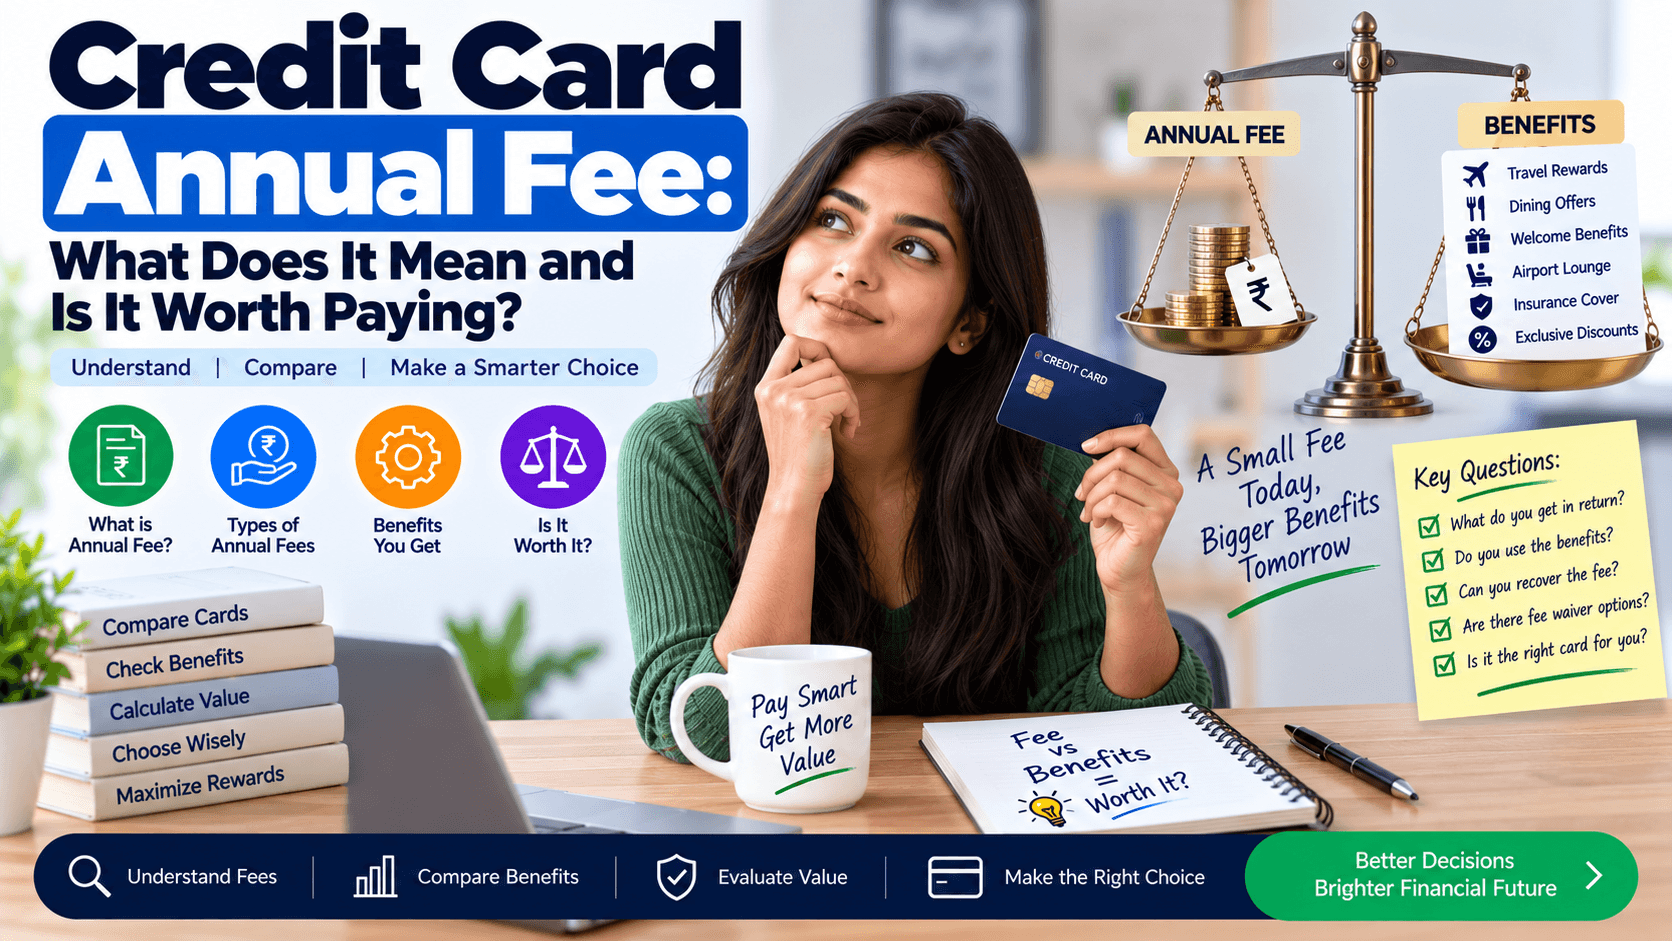
An annual fee is a fixed amount charged by the bank or card issuer every year for the privilege of holding a particular credit card. In India, these fees can range from as low as ₹199 to over ₹5,000 for premium cards that offer extensive rewards, lounge access, and travel insurance.
Banking institutions use the fee to cover the cost of additional services that come with the card. These may include:
Reward points and cashback programs
Airport lounge access
Travel and purchase protection insurance
Concierge services and exclusive offers
For premium cards, the fee also helps offset the higher cost of providing these perks.
The fee is usually added to your credit card statement on a specific date each year – often the anniversary of the card’s issuance. If you don’t pay it, the card may be downgraded to a no‑fee version, or you could incur a penalty interest.
List the card’s key features and rank them based on how often you would use them. For example, if you travel frequently and the card offers complimentary lounge access worth ₹2,000 per visit, the benefit may quickly offset a ₹2,500 fee.
Convert non‑cash benefits into rupees. A common method is:
Cashback / reward points: Multiply points by the redemption value (e.g., 1 point = ₹0.25).
Lounge access: Estimate the number of visits per year and multiply by the typical lounge fee (₹1,500–₹2,500).
Insurance coverage: Look at the sum insured and consider the probability of a claim.
If the total value exceeds the fee, the card is financially justified.
Many Indian banks offer no‑fee cards that still provide decent rewards. Compare the net benefit (benefits minus fee) of both cards before deciding.
Some banks waive the annual fee if you meet criteria such as:
Spend a minimum amount (e.g., ₹1,00,000) in a year
Maintain a savings or fixed‑deposit balance with the bank
Hold a specific number of co‑branded loyalty points
Meeting these conditions can make a high‑fee card effectively free.
The amount you pay as an annual fee could be invested elsewhere – for instance, a fixed deposit at 6% p.a. over a year on ₹5,000 yields ₹300. Compare this potential earnings with the card’s benefits.
Review your spending patterns each year. If you notice you aren’t using the card’s premium perks, consider downgrading.
Negotiate with the bank. A polite call can sometimes secure a fee waiver, especially if you have a good repayment record.
Set a reminder. Mark the fee‑charging date on your calendar so you can decide whether to keep or cancel the card before the charge appears.
Use multiple cards wisely. Keep a no‑fee card for everyday purchases and a premium card for travel or big-ticket spending to maximize rewards.
Monitor promotional offers. Banks frequently run fee‑waiver promotions for new customers – plan your application accordingly.
Myth 1: All annual fees are a waste of money.
Reality: When the card’s benefits align with your lifestyle, the fee can be more than justified.
Myth 2: Paying the fee guarantees high rewards.
Reality: Rewards are earned based on spending patterns; the fee does not magically increase points.
Myth 3: Once you pay, you’re stuck with the card.
Reality: You can switch to a no‑fee version or cancel the card after the fee is billed, though it may affect your credit score if not managed properly.
Decide based on a simple equation: Net Benefit = (Monetary Value of Perks) – (Annual Fee + Opportunity Cost). If the result is positive and aligns with your financial goals, the fee is worth paying. If not, explore fee‑waiver options or switch to a no‑fee alternative.
Remember, the best credit card is the one that supports your spending habits without costing you more than it returns.