Choosing the right credit card can feel like a maze, especially with the myriad of cashback and rewards options available in India today. While both types promise benefits, they work in different ways and suit different spending habits. This guide breaks down the core differences, highlights the pros and cons, and provides actionable tips to help you decide which card aligns best with your financial goals.
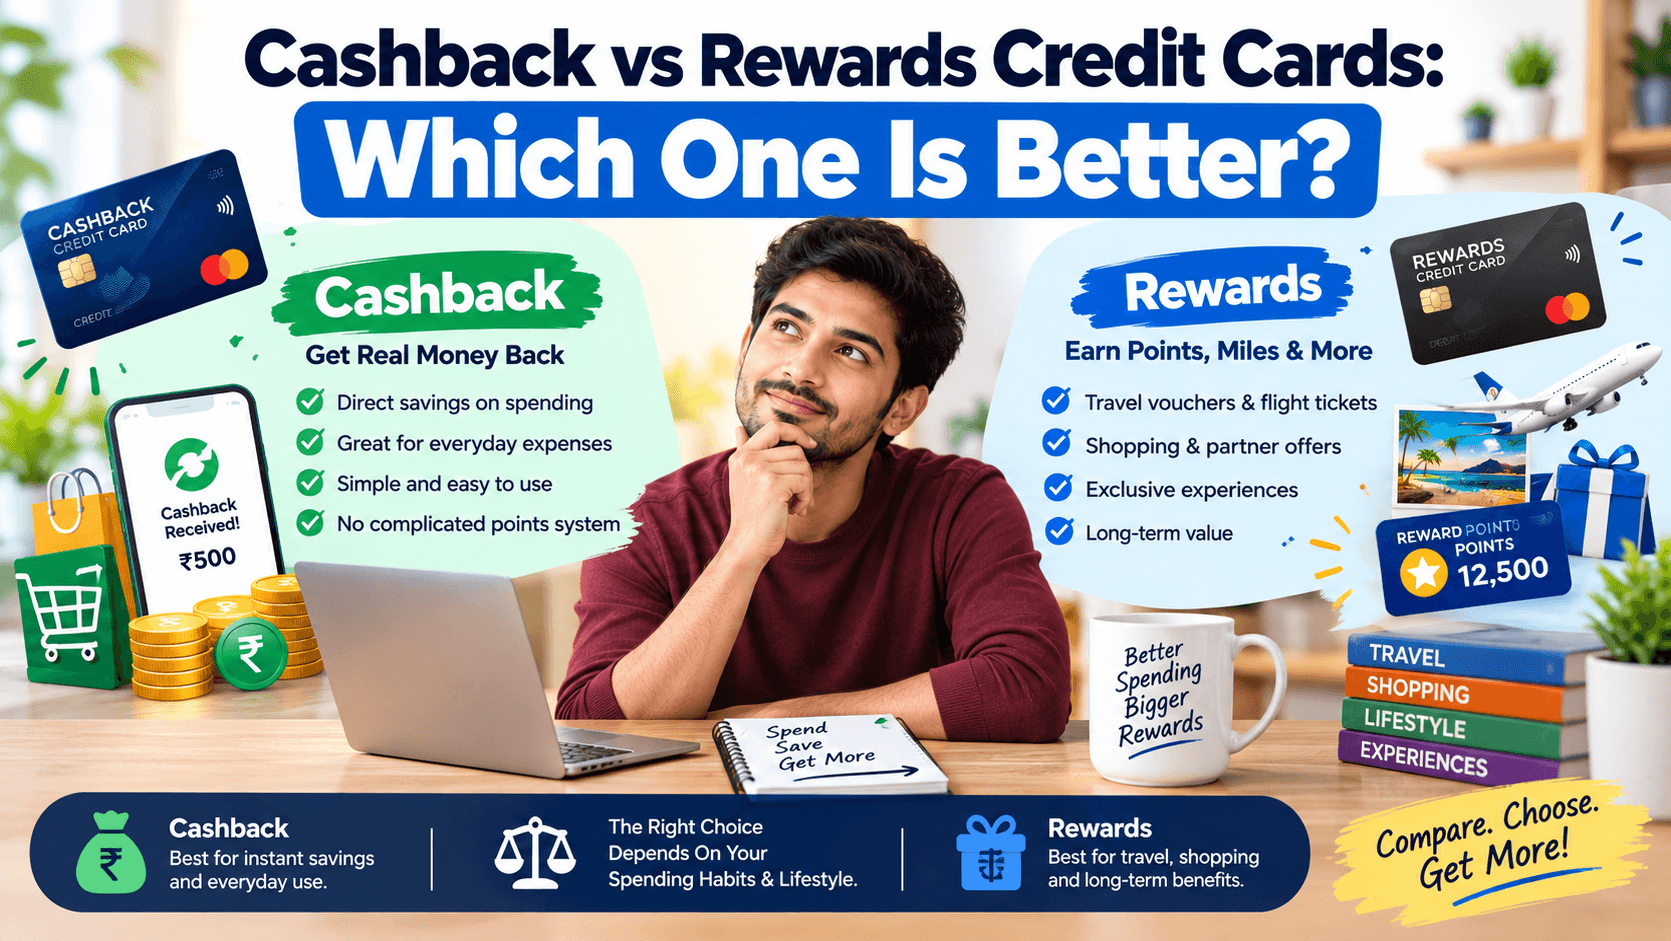
A cashback credit card returns a percentage of every rupee you spend directly to your account, usually as a statement credit or bank transfer. The cashback rate varies by category (e.g., 5% on groceries, 2% on utility bills) and can be flat across all purchases.
Simple reward structure: You earn a fixed % back on eligible spend.
Easy redemption: Cashback is automatically credited, no points to convert.
Lower annual fees: Many Indian cashback cards have nominal or zero annual fees.
If your monthly expenses are spread across everyday categories—groceries, fuel, online shopping, and bill payments—a cashback card often delivers a higher effective return because you earn back on every transaction.
Rewards credit cards award points for each rupee spent. These points can be redeemed for a variety of options: airline miles, hotel stays, merchandise, gift vouchers, or even converted into cashback.
Flexible redemption: Points can be used for travel, shopping, or cash.
Higher earn rates on specific categories: For example, 4X points on travel, 3X on dining.
Often bundled with travel perks: Airport lounge access, complimentary insurance, etc.
If you travel frequently, dine out often, or prefer to convert points into high‑value airline miles, a rewards card can outperform a cashback card. The value of points varies, so it’s crucial to calculate the effective rate based on your redemption choice.
AspectCashback CardRewards CardReward TypeCash (₹)Points / MilesRedemption SimplicityAutomatic, no effortRequires conversion or bookingBest ForEveryday spend, low‑maintenance usersTravel enthusiasts, high‑spending on specific categoriesTypical Annual Fee₹0‑₹1,000₹1,000‑₹2,500 (often justified by travel perks)Potential Earn Rate0.5%‑5% cash back0.5%‑3% equivalent cash value (depends on redemption)
List your top 5 expense categories and the average monthly amount you spend on each. Then, calculate the potential cashback versus points earned using the card’s rate tables. Use a simple spreadsheet to compare.
Subtract the annual fee from the total annual reward value. A high‑fee rewards card may still be worthwhile if you earn enough travel points to offset the cost.
Many Indian banks offer rotating quarterly categories (e.g., 5% on groceries for three months). If you can align your spend with these bonuses, a rewards card may give a temporary edge.
If you prefer instant, hassle‑free benefits, cashback is the clear winner. If you are comfortable navigating airline portals and can plan travel in advance, rewards can deliver higher value per rupee.
Some cards bundle complimentary insurance, fuel surcharge waivers, or lounge access. Even if the base reward rate is lower, these add‑ons can tip the balance.
HDFC Bank MoneyBack Card: 5% cash back on online spends, 1% on all other purchases, ₹500 annual fee (waivable on spend).
SBI Card ELITE: 2% cash back on utility payments, 1% on all else, plus travel benefits.
Axis Bank Insta Easy Cashback Card: Flat 0.5% cash back, zero annual fee.
HDFC Bank Diners Club Black: 5X points on travel, 2X on dining, complimentary lounge access, ₹2,500 annual fee.
ICICI Bank Platinum Chip Card – Visa: 3X points on grocery, 2X on fuel, points convertible to airline miles.
Standard Chartered Manhattan Platinum: 5% cash back on grocery (a hybrid model) and 2X points on other spend.
Calculate your average monthly spend in each category.
Pick 2–3 cards (one cashback, one rewards) that align with those categories.
Run the numbers: (Cashback % × spend) – annual fee vs (Points value × spend) – annual fee.
Read the fine print for redemption limits, expiry, and foreign transaction fees.
Apply online via the bank’s portal; keep your credit score above 750 for better approval odds.
There is no one‑size‑fits‑all answer. If you want a straightforward, low‑maintenance benefit on everyday purchases, a cashback card is usually the better choice. If you travel often, enjoy premium perks, and are comfortable managing points, a rewards card can provide superior value. By analyzing your spending habits, accounting for fees, and weighing redemption flexibility, you can select a card that maximizes your financial return and fits your lifestyle.
Absolutely. Many Indian users carry a cashback card for daily expenses and a rewards card for travel or high‑value purchases, thereby extracting the best of both worlds.
No. Both are reward mechanisms and do not accrue interest. However, carrying a balance on any credit card will incur standard interest charges, which can quickly negate any earned rewards.
In India, rewards received as a discount on purchases are not taxable. However, if you receive cash equivalents exceeding ₹10,000 in a financial year, you may need to report them as income. Always consult a tax advisor for personalized advice.