Personal loans are a popular way for salaried Indians to meet short‑term financial goals such as wedding expenses, home renovation, or debt consolidation. However, the amount you can borrow isn’t arbitrary – banks and NBFCs use a set of criteria anchored primarily around your salary and repayment capacity. This guide demystifies the process, breaks down the key factors lenders consider, and equips you with practical tips to maximise your loan amount.
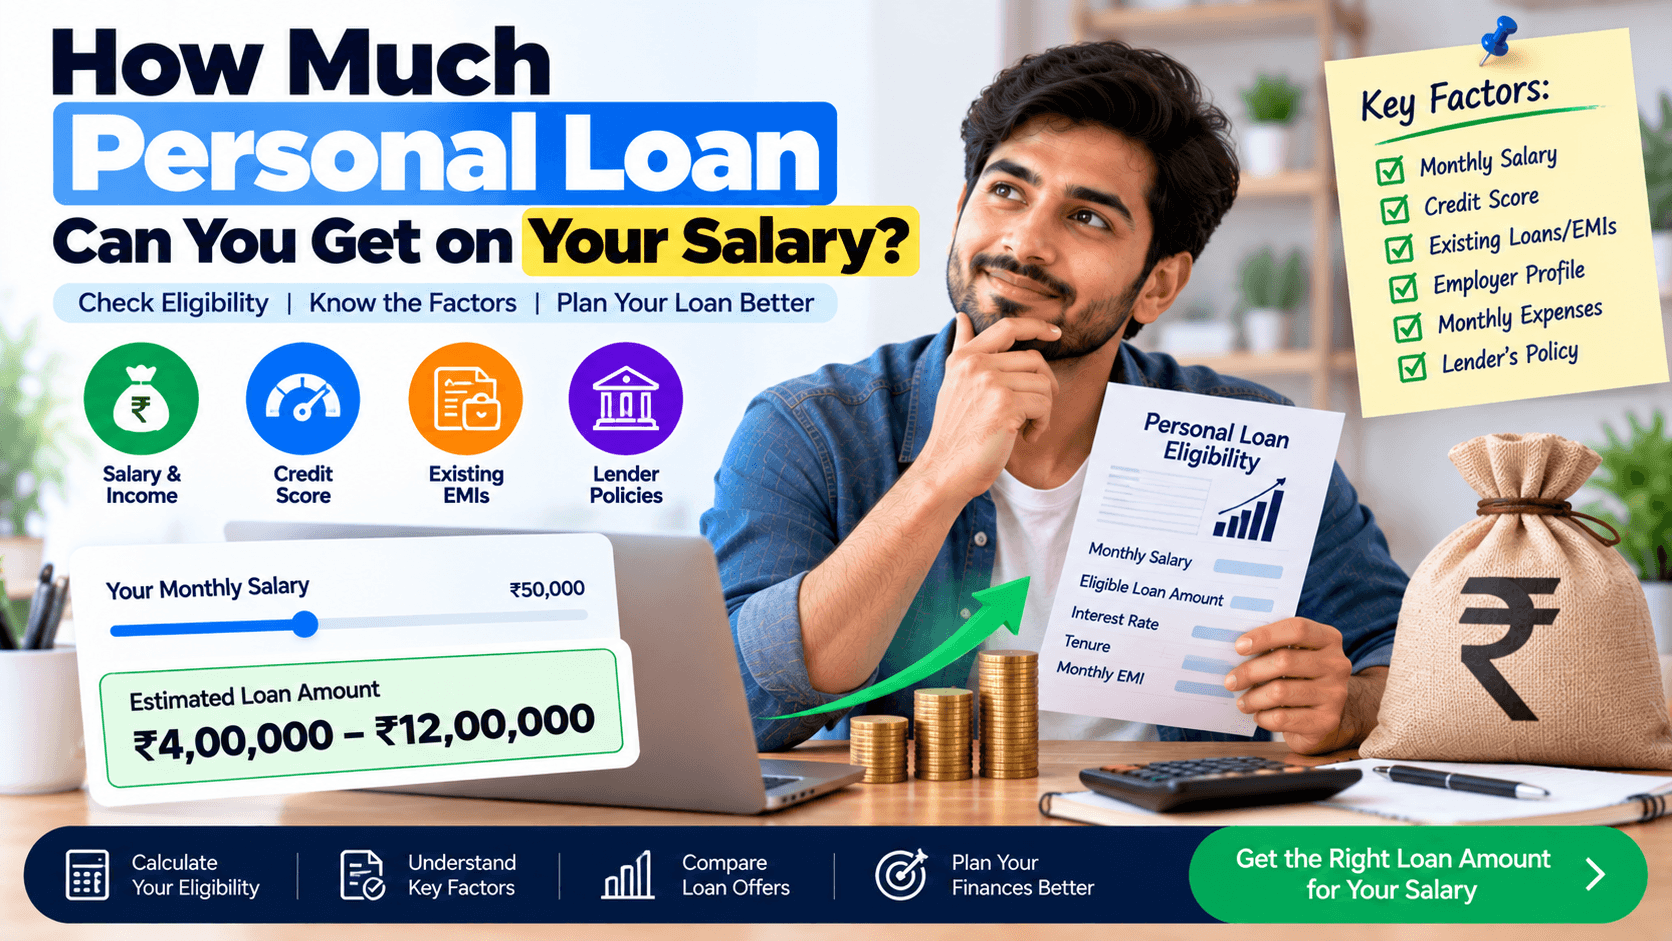
The most straightforward metric is your cost‑to‑company (CTC) or gross monthly salary. Lenders typically use a multiple of your monthly income to determine the maximum loan size. The common range in India is:
2–4 times your monthly CTC for salaried professionals with a stable job.
Up to 5–6 times for higher‑earning executives or those with additional income sources (rental, freelance).
Example: If your CTC is ₹60,000, you can expect a loan window of ₹1.2 lakh to ₹2.4 lakh, subject to other criteria.
Lenders assess how much of your income is already committed to existing EMIs (home loan, car loan, credit cards). A healthy DTI is typically below 40‑45%. The formula is:
DTI = (Total Monthly EMI Obligations ÷ Gross Monthly Income) × 100
If your DTI exceeds the threshold, the bank may reduce the loan amount or decline the application.
A credit score of 750+ positions you for higher loan limits and lower interest rates. Scores below 650 can lead to stricter limits or the need for a co‑applicant.
Most lenders require a minimum of 12‑24 months in the current job. Longer tenure (especially >3 years) signals stability and can push the loan multiple higher.
Eligibility ages usually range from 21 to 60 years. The remaining tenure until retirement (or the bank's loan‑repayment cap of 60‑65 years) caps the maximum loan tenure, indirectly affecting the loan amount you can comfortably repay.
While each bank has its own model, a simplified version looks like this:
Maximum Loan = (Monthly Income × Income Multiple) – Existing EMIs
Let’s walk through a real‑life example.
Monthly CTC: ₹80,000
Income Multiple: 4 (typical for mid‑range salaried professionals)
Existing EMIs: Home loan ₹12,000 + Credit card EMI ₹3,000 = ₹15,000
Calculation:
(80,000 × 4) – 15,000 = 320,000 – 15,000 = ₹3,05,000
In this scenario, the borrower could be approved for a personal loan of roughly ₹3.05 lakh, provided the credit score and tenure criteria are met.
Boost Your Credit Score: Pay credit card balances in full, avoid missed EMI payments, and keep credit utilization below 30%.
Reduce Existing Debt: Clearing or consolidating high‑interest loans before applying can lower your DTI dramatically.
Show Additional Income: Include verified side‑income (freelance, rental) with proper documents; many banks consider it in the income multiple.
Maintain Stable Employment: Avoid job hopping close to the application date. If you’ve just joined a new firm, consider waiting a few months.
Choose the Right Lender: Some NBFCs are more flexible with income multiples for young professionals, while traditional banks may offer lower rates for high credit scores.
Opt for a Shorter Tenure: A shorter loan tenure reduces the risk for the lender, often translating into a higher approved amount.
Only a handful of premium credit cards or specialized loan products claim such high multiples, usually with stringent credit score requirements and collateral. For most salaried borrowers, 2‑5 times is realistic.
p
Joint applications can increase the loan amount, but banks evaluate each applicant’s credit profile separately. Both incomes are added, yet the combined DTI and credit scores still apply.
Check your CIBIL score online (free once a year).
Gather documents: salary slips (last 3 months), Form 16, bank statements (last 6 months), PAN, Aadhaar, and proof of residence.
Use online loan calculators (most banks provide them) to estimate your eligible amount and EMI.
Submit a pre‑approval request on the bank’s website – it’s usually a soft inquiry and won’t affect your credit score.
Compare offers (interest rate, processing fee, pre‑payment charges) before finalising.
Complete the full application, provide any additional documents, and await sanction.
Understanding how salary, existing liabilities, credit score, and employment stability interact is the key to unlocking a higher personal loan amount. By cleaning up your credit profile, managing existing debts, and presenting a stable income story, salaried Indians can comfortably secure loans that align with their financial goals.
Remember, the goal isn’t just to get a larger loan – it’s to get a loan you can repay without stress. Use the tips above, run the calculations, and approach the lender that best matches your profile for a smooth borrowing experience.